There's a particular kind of dread that shows up for me around late December. It's not about any one bill. It's the vague, foggy feeling of not quite knowing where everything stands – which subscriptions are still running, what that annual charge in February was again, whether I actually saved anything this year or just felt like I did.
For a long time I avoided that fog by… not looking. Which, as you can guess, only made the fog thicker. What finally helped was turning the whole thing into one calm, timed hour at the end of the year: a candle, a cup of tea, my laptop and a checklist that tells me exactly what to do for each block of minutes. No spreadsheets with forty tabs. No shame. Just clarity.
This is that hour. Below you'll find a year-end money reset you can finish in 60 minutes, broken into eight short blocks with a timed checklist table, a walk-through of each step, a few gentle habits to carry into the new year and some kind words for the moments when money makes your stomach drop. It's all about habits and awareness – the boring-but-lovely basics that make everything else easier.
A quick note: I'm not a financial professional, and this is not financial advice. It's a gentle habit routine for getting organized. For decisions about investing, debt, taxes or retirement, please talk to a qualified professional.
What a Year-End Money Reset Is (and Isn't)
A money reset is a once-a-year check-in where you look at your whole financial picture, tidy up what's messy and set up a few small habits for the year ahead. Think of it like a deep clean for your finances – not a renovation.
It is:
- A snapshot of where things stand today
- A sweep for forgotten subscriptions and sneaky recurring charges
- A look at your spending patterns, without judging them
- A chance to plan for known costs that always seem to "surprise" you
- One or two tiny automations that make next year easier
It isn't:
- Investing advice or a plan to "get rich"
- A strict budget you'll feel guilty about breaking
- A verdict on whether you're "good" or "bad" with money
If you only remember one thing: the goal of this hour is awareness, not perfection. Knowing your numbers – even uncomfortable ones – is calmer than guessing.
Before You Start: Set the Scene
I know it sounds silly to "set the scene" for money admin, but it makes a real difference. When something feels stressful, making it pleasant is half the battle. Here's what I'd gather before the timer starts:
- Your laptop or phone with access to your bank and card apps (log in ahead of time so you're not resetting passwords on the clock).
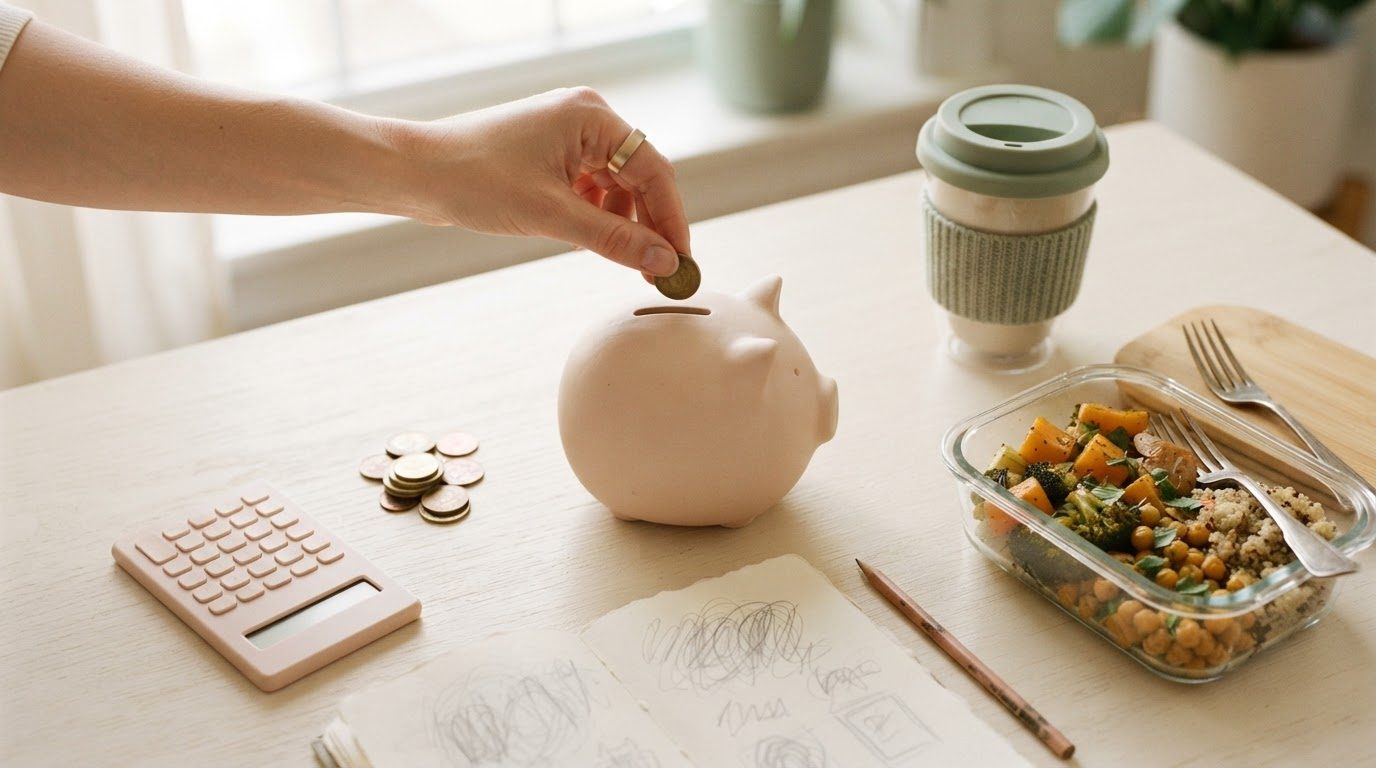
- A notebook and pen. A simple budget planner notebook with monthly pages is nice if you want to keep your reset notes in one place all year, but any notebook works.
- A drink you love. Evening tea for me – coffee sometimes perks me up and sometimes makes me jittery, and this is not the hour for jitters.
- A candle or soft lamp. A neutral candle in a glass jar on the table quietly tells your brain, "This is a calm thing."
- A timer. Your phone timer is perfect. The timer is what keeps this from turning into a three-hour spiral.
Pick a time when you won't be interrupted – a quiet weekend morning or a weeknight after dinner. Some people like to do it with a partner or a friend doing their own reset at the same time, like a money study date.
The 60-Minute Year-End Money Reset Checklist
Here's the whole hour at a glance. Copy it into your notebook or keep this page open next to you. Each block has a clear "done when" so you know when to stop and move on – that's the part that keeps it gentle.
| Time | Block | What to do | Done when… |
|---|---|---|---|
| 0–5 min | Settle in | Light the candle, open your apps, write today's date and one sentence about how you feel about money right now | You're logged in and your notebook is open |
| 5–15 min | Snapshot | List every account and its current balance: checking, savings, credit cards, loans, any retirement or savings accounts | You have one page with every balance on it |
| 15–25 min | Subscription sweep | Scan the last two months of statements for recurring charges; mark each keep, pause or cancel | You've cancelled or paused at least one thing you don't use |
| 25–35 min | Spending look-back | Skim the last three months and jot rough totals for 4–6 categories (home, groceries, transport, eating out, shopping, fun) | You can name your top two spending categories |
| 35–42 min | Known costs list | Write down yearly and irregular costs coming next year: renewals, insurance, gifts, trips, car care, annual fees | You have a list with rough amounts and months |
| 42–50 min | One small automation | Set up or adjust one automatic transfer to savings, or one autopay for a bill you sometimes forget | One automation is live |
| 50–55 min | Paper tidy | Clear your wallet, toss old receipts you don't need, file anything important in one folder | Your wallet closes easily and papers have one home |
| 55–60 min | Intentions | Write three gentle money intentions for the new year and one thing you did well this year | The page is done and you blow out the candle |
That's it. Sixty minutes. You don't need to finish every block perfectly – if the subscription sweep takes 15 minutes instead of 10, borrow from the paper tidy and do that part another day.
Walking Through Each Step
Here's a little more detail for each block, plus what to do if a step makes you want to hide under the blanket.
0–5 Minutes: Settle In
Light the candle, open your banking apps and write today's date at the top of a fresh page. Then write one honest sentence about how money feels right now. "I'm nervous to look." "I think I did better this year." "I have no idea." All are fine.
This tiny step matters more than it seems. Naming the feeling takes some of the power out of it, and it gives you something to compare against next year.
5–15 Minutes: Take a Snapshot
Make a simple list of every account you have and its balance today. Checking, savings, every credit card, any loans, any retirement or savings accounts you might have through work. Just the number next to the name – no math yet.
If you find an account you forgot about (it happens more than you'd think), write it down too. At the bottom, you can add up what you have and what you owe if that feels okay. If it doesn't feel okay today, skip the totals. The list itself is already a win. (A simple white desk calculator next to your notebook keeps you off your phone, where notifications love to pull you away mid-sum.)
If it feels scary: look at one account, write the number, take a breath, then do the next. The number was already true before you looked. Looking just means you get to make decisions with real information.
15–25 Minutes: Subscription Sweep
This is the most satisfying block, I promise. Open your last two months of bank and card statements and look for anything that repeats: streaming services, apps, cloud storage, memberships, boxes, free trials that quietly turned into paid ones.
Next to each one, write keep, pause or cancel. My rule of thumb: if I haven't opened it in the last month and wouldn't sign up for it again today, it goes. Cancel at least one thing before the block ends. That alone often pays for a nice candle or two each month.
Tip: streaming services are easy to rotate. Keep one at a time, binge what you want, cancel, switch to the next.
25–35 Minutes: Spending Look-Back
Skim your last three months of spending and sort it into a handful of rough categories: home and bills, groceries, transport, eating out and coffee, shopping, and fun. You don't need exact numbers – rounding to the nearest ten or twenty is perfectly fine.
I like to give each category its own color with pastel highlighters on a printed statement – it turns a wall of numbers into something your eyes can actually read. Then ask yourself two questions:
- Which two categories are the biggest?
- Is there one spend that made me genuinely happy, and one I barely remember?
That second question is gold. The point isn't to cut everything you enjoy. It's to spend more on the things you love and less on the things you don't even notice. If you'd like a place to keep tracking this through the year, my free finance tracker printable keeps it to one calm page a month.
35–42 Minutes: List Your Known Costs
So many "money emergencies" aren't emergencies at all – they're things that happen every year that we simply forget about. Write down everything you know is coming next year that doesn't happen monthly:
- Annual subscriptions and membership renewals
- Insurance payments that come once or twice a year
- Birthdays, holidays and gifts
- Trips and weddings you're likely to attend
- Car care, registration or bike repairs
- Haircuts, checkups and other regular appointments
- Annual card or account fees
Add a rough amount and the month next to each one. Then, if it feels doable, add them all up and divide by 12. That's the amount you'd set aside each month so none of these surprise you. Many people call this a sinking fund – a small pot of money you fill slowly for costs you know are coming.
42–50 Minutes: Set Up One Small Automation
Just one. Pick whichever feels most helpful:
- An automatic transfer to savings the day after payday – even a small amount builds the habit.
- An automatic transfer into your sinking fund for those known costs.
- Autopay for a bill you've paid late before (at least the minimum, so a busy week never costs you a late fee).
Automation is the kindest money habit there is, because it doesn't rely on willpower or memory. You decide once, and future-you benefits every month. My easy ways to save money every day have more small ideas if you want to go further later.
50–55 Minutes: Paper Tidy
Empty your wallet onto the table. Toss old receipts you don't need, remove expired cards (cut them up first), and put the gift cards you forgot about somewhere you'll actually use them. Then gather any important papers lying around – tax documents, warranties, insurance letters – into one folder.
A pretty accordion file organizer with labeled sections is a lovely way to give every paper a home. When everything lives in one place, next year's reset will take half the time.
Safety note: shred anything with account numbers or personal details before throwing it out, rather than putting it straight into the recycling.
55–60 Minutes: Write Your Intentions
Finish on a soft note. Write down three gentle money intentions for the new year – habits, not huge targets. For example:
- "Check my balance every Friday morning with my coffee."
- "Wait 48 hours before buying anything non-essential over a set amount."
- "Have a 20-minute money date on the first Sunday of each month."
Then write one thing you did well with money this year. Maybe you paid something off, maybe you cooked at home more, maybe you finally opened that savings account. It counts. Blow out the candle. You're done.
Gentle Money Habits To Carry Into the New Year
The reset gives you a clean slate. These small habits keep it clean without needing another big session every month.
- A weekly 5-minute balance check. Same day, same time. Friday morning works well because you see the week before the weekend spending starts.
- A monthly 20-minute money date. A shorter version of this reset: snapshot, subscriptions, one look at spending. Put it in your planner as a recurring event.
- The 48-hour pause. For anything that isn't essential, leave it in the cart for two days. You'll be surprised how often the urge simply passes.
- Name your savings pots. "Spring trip" or "Winter weekend away" feels much more motivating than "Savings 2". Many banks let you rename accounts or create separate pots.
- Plan your free fun. When you plan lovely no-cost things – walks, library visits, a picnic – you spend less without feeling deprived. Here are some things to do by yourself without spending money to start your list.
- One "unsubscribe" a week. Unsubscribe from one store email list every week. Fewer sale emails, fewer impulse buys.
- Celebrate small wins. Paid off a card? Hit a savings milestone? Mark it with something small and free, like a long bath or an evening with a favorite movie.
If you're doing a bigger end-of-year tidy across your whole life, this hour slots right into my new year reset checklist, and it pairs nicely with choosing a money goal from my goals for the new year list.
If Money Makes You Anxious
Here's a small honest admission: I'm prone to anxiety, and money is one of those topics that can make my heart race before I've even opened an app. If that's you too, here's what helps me:
- Do it in daylight, not at midnight. Everything looks scarier late at night.
- Look at one number at a time. You don't have to take in the whole picture in one gulp.
- Separate facts from stories. "I have $X in savings" is a fact. "I'm terrible with money" is a story. Write the facts, gently question the stories.
- Breathe before you click. In for four, out for six, three times. Then open the app.
- Remember that awareness is progress. Every person who has ever turned their finances around started by looking.
And please be kind with yourself if the numbers aren't where you'd like them. Money is tied up with so much – where we grew up, what we were taught, life events none of us choose. If you're dealing with debt that feels unmanageable, a nonprofit credit counselor or a qualified financial professional can help you see options you might not know about. Asking for help is a smart move, not a failure. And if money worry is affecting your sleep or mood for weeks at a time, it's worth talking to someone you trust or a mental health professional too.
One more small comfort: keep a big cream ceramic mug just for your money dates. It sounds sweet and a little silly, but having a ritual object makes the whole thing feel like self-care instead of a chore.
Make It a Yearly Ritual
The first reset is always the longest and the most emotional. The second one, a year later, feels completely different – you know where everything lives, you've already cancelled the worst subscriptions and you have last year's page to compare against. That comparison is one of the most encouraging things you'll ever read about yourself.
A few ways to make it stick:
- Pick the same week every year. The quiet days between the holidays and the new year work well for many people, but any week you can protect is perfect.
- Keep every reset page together. Same notebook, same folder. Over the years it becomes a little history of how far you've come.
- Do a mini version each season. A 20-minute snapshot and subscription sweep in spring, summer and autumn means the big December hour stays calm.
- Make it something to look forward to. Your favorite tea, a fresh candle, a playlist you only play for this. Small comforts turn a chore into a ritual.
Final Thoughts
You don't need to become a finance expert to feel calmer about money. You need one honest hour, a candle, a cup of tea and a checklist that tells you exactly what to do next. Snapshot, sweep, look back, plan ahead, automate one thing, tidy, intend. That's the whole reset.
Do it once before the year ends, and the new year starts with clarity instead of fog. Future-you will be so grateful you sat down and looked.